
I have had a few calls recently regarding this particular area of advice. It’s not something that is always relevant, or in the client’s best interest, but it’s important to still have knowledge of this and how it can be of use to your situation.
Granny flat arrangements — how they work
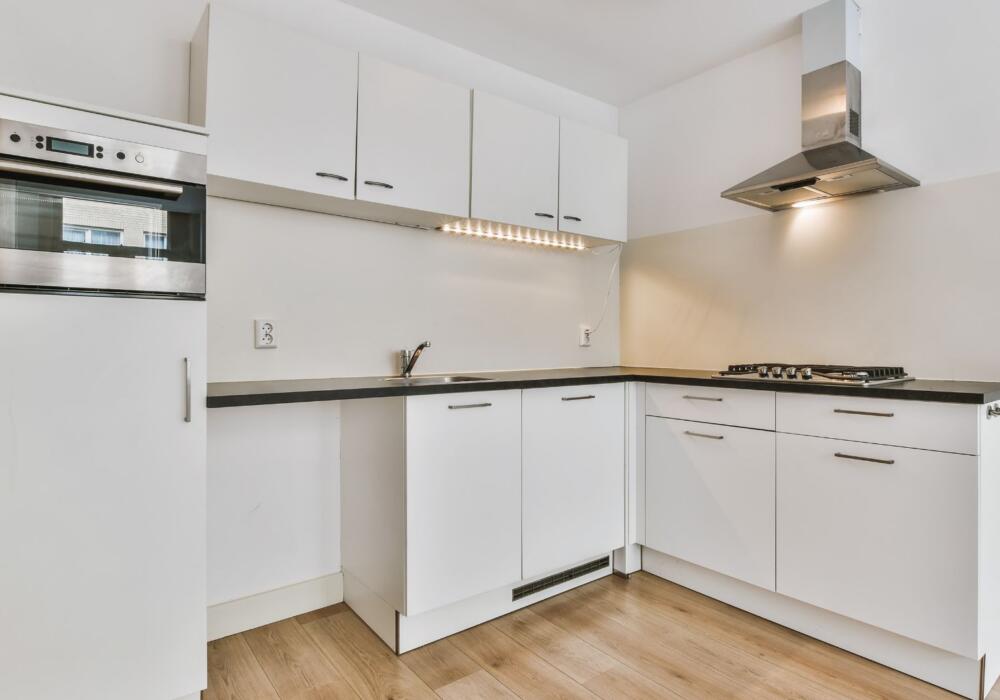
A granny flat arrangement is when an older person pays for the right to live in a property — often a family member’s home, or a purpose-built flat on their land — usually in exchange for a lump sum, or by transferring assets or income. It’s a legal concept, not necessarily a physical structure.
A few things worth knowing:
- It doesn’t have to be a granny flat in the literal sense. It just needs to meet the definition of a “granny flat interest” under Centrelink rules.
- The amount paid is compared against a “reasonableness” test. If someone pays more than that assessed value, the extra can be treated as a deprived asset — which may affect pension entitlements for a period.
- Get the value wrong and it can also create Centrelink asset or income test issues down the track.
- Family arrangements can go wrong — it’s worth having something in writing, ideally with independent legal advice for all parties involved.
Benefits
- Can free up money for the older person — the lump sum paid by family can be used to fund aged care costs, boost retirement savings, or cover living expenses.
- Keeps family close — allows an older person to live near (or with) family rather than move into residential care, which many clients value for quality of life.
- Potential Centrelink advantage — if structured correctly, the value of a granny flat interest is typically exempt from the pension assets test (unlike cash or most other assets). This is a key reason clients look at it.
Things to consider
- Money is generally locked in — once paid, the amount is usually not recoverable if the family relationship breaks down, the older person needs to move to care later, or the family member’s circumstances change (e.g. divorce, bankruptcy).
- No legal ownership or tenancy right — unless it’s formally documented, the older person may have no enforceable right to stay, which creates real risk.
- Deprivation risk if overpaid — paying more than the “reasonableness” value can trigger deprivation rules and affect pension entitlements for a period.
A few more things worth flagging that don’t fit neatly into benefits/disadvantages:
- It affects homeowner status. For social security and aged care purposes, a granny flat interest generally makes the person a “homeowner” — which changes which asset test threshold applies and how aged care fees are calculated. Worth spelling out, since clients often don’t realise this cuts both ways.
- CGT can apply to the person giving up the property. If a parent transfers title (or a share of it) in exchange for the right to reside, there may be capital gains tax consequences for them — this is a common blind spot and worth a tax agent/accountant referral.
- The reasonableness test sets a ceiling. Centrelink has a formula for what’s considered a “reasonable” amount to pay for a granny flat interest, based on the person’s age and life expectancy. Anything paid above that amount is assessed as a deprived asset (and subject to deeming) — this is often where clients get caught out without realising.
- The five-year rule cuts both ways. If the arrangement ends within five years — whether by choice, relationship breakdown, or a move into aged care — Centrelink can go back and reassess it, particularly if the reason for leaving could have been anticipated when the arrangement was set up (e.g. already had an ACAT aged care approval).
- Family fallout is the quiet risk. Even where the Centrelink and tax side is done properly, these arrangements can create real tension — especially with other family members who aren’t part of the deal. Worth raising as a conversation point, not just a numbers one.
If you are wanting more advice in this area and how it could be relevant to you, book an appointment with me to chat more
This article contains information that is general in nature. It does not take into account the objectives, financial situation or needs of any particular person. You need to consider your financial situation and needs before making any decisions based on this information